

Cash App
4.7

I find the most useful way to judge Cash App is to look at its central promise: moving money between people without turning a small everyday payment into a banking chore. That simple job is where the app makes the clearest case for itself. It is a free finance app from Block, Inc., and its mix of payments, bitcoin, investing, and banking tools makes it broader than a basic payment wallet. The breadth is convenient, but it also means you should decide which parts you actually want to use rather than treating every feature as equally essential.
When a quick payment is the main event
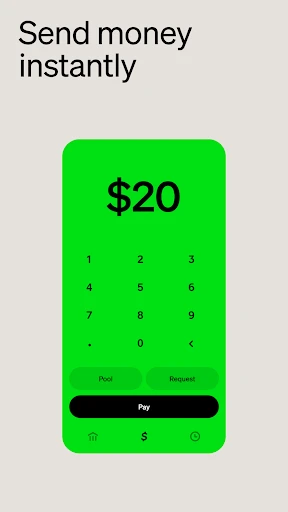
Peer-to-peer payments are easiest to appreciate when the amount is ordinary and the people involved already use the app. Think of a shared lunch: one person pays, everyone else sends their portion, and the person who covered the bill does not have to chase cash. The same pattern works for splitting a household purchase or settling a small amount with a friend. In those moments, having the payment app ready on your phone can feel more natural than arranging a bank transfer for every little expense.
The important practical question is not only whether you can send money, but whether the person you are paying can receive it in a way that suits them. Cash App works best when it is already part of the group’s routine. If your friends or family prefer another payment service, asking them to adopt a new one for a single transaction can create more friction than the app removes. I would keep a backup payment method for those cases instead of assuming one app will work for every person and every bill.
A useful everyday workflow
For a regular shared expense, I would use a simple habit: agree on the amount first, check the recipient carefully, and send the payment only when the details look right. That small pause matters with any instant-style payment tool because a convenient interface can make it tempting to tap through quickly. I also find it sensible to keep payment notes clear enough that both people can recognize what a transfer was for later. That is especially helpful when several small social payments happen close together.
One less obvious benefit of combining payments with a balance and a card is that the app can fit into a short chain of actions. Money received from someone can remain in the account for later spending rather than requiring you to immediately move it elsewhere. If you use the Cash Card, that can make the balance feel practical for day-to-day purchases. The trade-off is that a convenient balance is not automatically the same thing as a complete replacement for a traditional bank account; I would first decide what role I want it to play in my finances.
The All-in-One Financial Tool
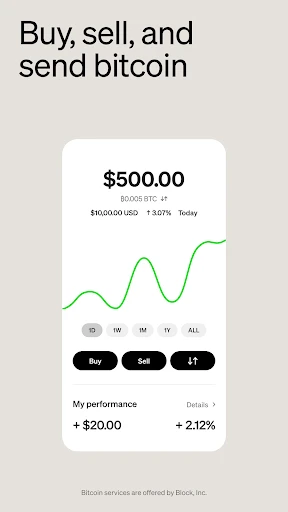
Cash App isn't just about sending and receiving money; it's a full-blown financial ecosystem. You can buy, sell, and hold Bitcoin, invest in stocks, and even get a debit card that gives you instant access to your funds. It's like your wallet, bank, and investment portfolio all rolled into one.
Ease of Use
Setting up Cash App was smoother than a well-blended smoothie. Seriously, just a few taps and you're in. The interface is clean and intuitive, so you won’t get lost in a maze of buttons. Whether you’re a tech wizard or a newbie, you’ll find it a breeze to navigate.
That approachable layout is useful when I want to complete one clear task, such as checking a balance or making a payment, without opening a full online banking site. Still, simple navigation should not be confused with a simple financial decision. Sending money, buying an investment, and purchasing bitcoin are different activities with different risks. I would take a moment to confirm which section I am using before committing money, especially if I am moving quickly between the app’s tools.
Features That Shine
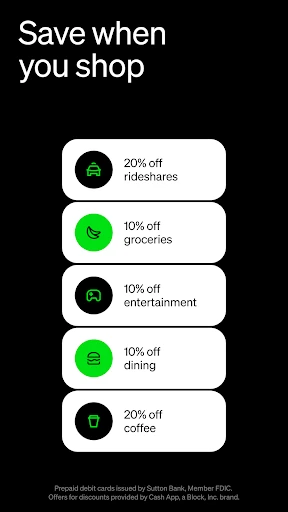
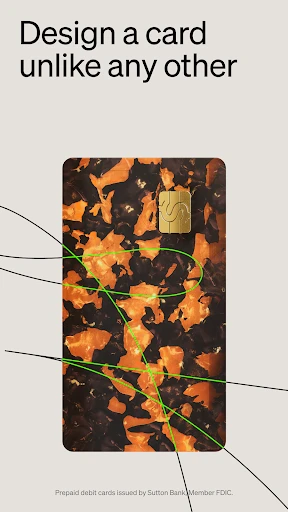
One of the coolest features is the Cash Card. This customizable debit card lets you spend your Cash App balance anywhere Visa is accepted. Plus, you can add "Boosts" to your card, which are basically instant discounts at popular stores. Who doesn't love saving a few bucks?
I would treat Boosts as a bonus rather than a reason to spend. A discount only helps if the purchase was already on your list, and the value of any offer depends on whether it matches your normal shopping. Before relying on a particular Boost, I would check the terms shown in the app and make sure it applies to the purchase I have in mind. That keeps a handy card perk from quietly becoming an excuse to buy something unnecessary.
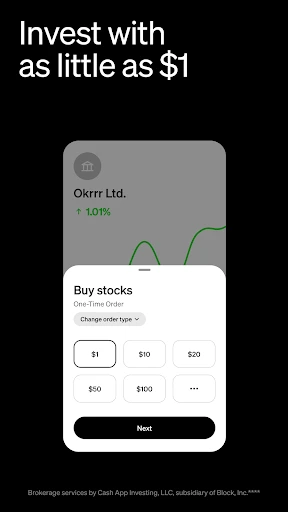
If you're into investing, the app lets you buy fractional shares of stocks. No need to be a Wall Street tycoon to get started. Just a few dollars and you can own a piece of your favorite company.
Fractional investing can make it easier to begin with a small amount, but it does not make a stock predictable or remove the possibility of losing money. I would use this feature only after deciding how much I can afford to put at risk, and I would avoid treating a familiar company name as a substitute for research. For someone who wants a carefully planned, diversified portfolio or extensive research tools, a dedicated investment service may be a better fit than a payment-first app.
Security and Privacy
In this digital age, security is key, and Cash App gets it. The app uses encryption and fraud detection technology to keep your money safe. Plus, you can enable security features like Face ID or a passcode for an extra layer of protection.
Those safeguards are useful, but my own habits still matter. I would enable a screen lock, keep access to the phone private, and double-check the recipient before sending money. A payment app can help protect an account, yet it cannot make every mistaken payment or poor decision harmless. I would also avoid sharing private account details in messages just because a payment conversation feels casual.
Customer Support
Now, no app is perfect, and sometimes things can go south. But fear not! Cash App offers responsive customer support. Whether you prefer email or a quick chat within the app, they’ve got your back.
For any money app, I think it is wise to know where the in-app help options are before a problem appears. If a payment is delayed or something looks unfamiliar, I would start with the transaction details and the app’s support route rather than relying on a message from someone claiming they can fix it. That is a general precaution, not a reason to expect trouble: keeping the conversation inside the official app makes it easier to stay oriented.
Who Is It For?
Whether you're splitting the dinner bill, paying rent, or investing in your future, Cash App is designed to make money matters simple and efficient. It’s perfect for anyone looking to streamline their finances without the hassle of traditional banking.
I would be more cautious about calling it a fit for every rent payment. Before using any payment app for a recurring or important bill, confirm that the recipient accepts that method and that you understand how the payment will be recorded. A landlord or service provider may expect a different process, and a familiar person-to-person payment flow is not automatically ideal for formal bills. For rent, I would prioritize a clear record and an agreed payment method over convenience alone.
How it compares with other money tools
Compared with a bank’s own app, Cash App feels more centered on quick person-to-person transfers and a compact collection of money features. A bank app is usually the more natural home for managing an established account, reviewing a broader set of banking activity, or keeping financial tasks under one institution. Cash App’s appeal is that it can make small payments and a few adjacent activities feel accessible in one place. The better choice depends on whether you want a companion tool or the main hub for your finances.
Compared with a single-purpose payment wallet, Cash App offers more than sending and receiving money because it also brings a card, bitcoin, and stock investing into the same app. That range can reduce app-hopping if you genuinely use those options. It can also make the experience feel busier than a simple wallet. I would not choose it just because it has more features; I would choose it if the payment flow is useful to me and at least one of its additional tools fits a real routine.
Its audience is substantial: Cash App has a 4.7 average from around 4.1 million ratings and over 100 million installs. That reach suggests many people have made it part of their payment habits, but it does not guarantee that your own friends, billers, or preferred financial providers will use it. Before moving a regular payment routine over, I would test it with a small, low-stakes transaction and see whether the people involved find it convenient too.
Where the convenience has limits
The all-in-one approach is also the main trade-off. A payment balance, card spending, stock purchases, and bitcoin activity may sit close together, but they should not be mentally lumped into one pot. I would keep a simple personal boundary: money needed soon stays separate from money I am willing to invest, and speculative purchases stay small enough that a loss would not disrupt my plans. That distinction is more useful than trying to make one app serve as a complete financial plan.
There is also a social limitation: a payment tool is only frictionless when both sides are comfortable using it. For someone who regularly pays people who prefer cash, bank transfers, or another wallet, maintaining multiple methods may be unavoidable. If your priority is a familiar branch-based relationship, detailed budgeting, or a dedicated investment platform, I would look at those options first and use Cash App only for the part it handles well.
The app is free, rated for Everyone, and its current version is 5.35.0, with a minimum operating system requirement of 10. It was released on October 15, 2013, and is now developed by Block, Inc. Those details make it easy to understand why it is a familiar choice, but the practical decision is still personal: check that your device meets the requirement, then consider whether quick payments and the extra financial tools match how you actually manage money.
Who gets the most from it
I think Cash App is strongest for someone whose everyday life already includes friends or family who use it, who wants an easy way to settle casual payments, and who values having a card and optional investing tools nearby. It can be especially handy when small transfers are frequent enough that a separate bank workflow feels cumbersome. Someone curious about investing may also appreciate being able to start with fractional shares, provided they approach it as investing rather than a guaranteed way to grow money.
I would skip it as a primary financial home if you need a particular bank relationship, rely on payees who do not accept it, or want a specialist environment for long-term investing. I would also avoid using its investing and bitcoin tools simply because they are visible in the same place as payments. For me, the best version of the app is focused: use the payment feature when it saves effort, use the card if spending from the balance suits you, and treat investing as a separate decision that deserves care.
So, there you have it! If you're looking for an app that combines functionality with ease of use, give Cash App a try. It might just change the way you handle your money, one transaction at a time.
4.7
453.14K Reviews
Pros
- User-friendly interface for seamless navigation.
- Instant notifications for every transaction.
- No fees for basic money transfers.
- Supports Bitcoin and stock investments.
- Customizable cash card with unique designs.
Cons
- Limited customer support options available.
- Not available in all countries.
- Occasional account verification issues.
- Withdrawal limits can be restrictive.
- No joint accounts or shared wallets.


